Construction Machinery Protection
Plant and Equipment Insurance in Australia
Tell us about your machinery and equipment.
Construction Machinery Protection
Tell us about your machinery and equipment.
Construction businesses depend on machinery and equipment to excavate, lift, move materials and complete work. Damage, theft or a breakdown can disrupt operations and create replacement or repair costs. Plant and Equipment Insurance provides options for insuring specified machinery and equipment against particular risks, depending on the policy selected.
PCIC Insurance works with builders and contractors who want to consider cover for eligible owned or hired plant. The correct approach depends on the type of equipment, its value, where it operates, how it is transported and whether it is hired to or from another party. We can help you examine the policy terms relevant to those arrangements. Request a quote based on your actual equipment.
Insurers often ask how plant is stored, secured and maintained, and who operates it. Safe Work Australia construction guidance covers the safety duties for plant on construction sites, which is useful background when you describe your equipment and how it is used.
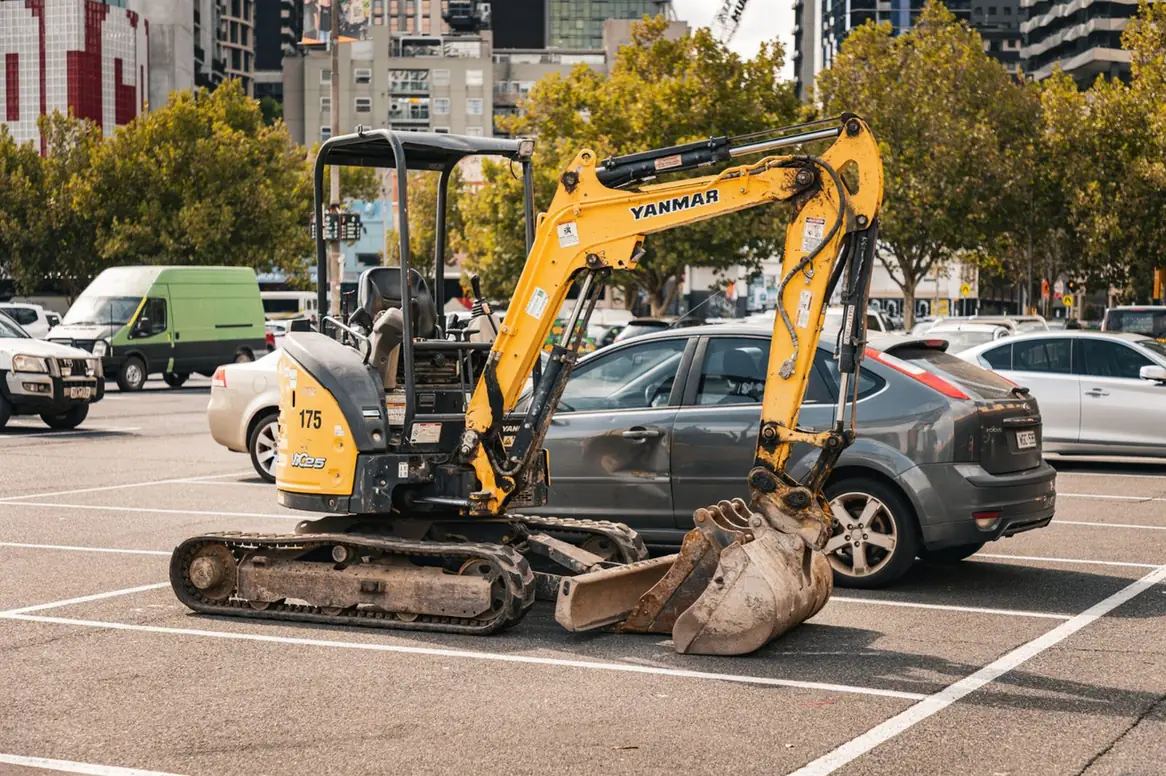
Plant insurance can involve mobile machinery, portable equipment, tools and specialised assets, but not every item belongs under the same policy. Insurers may distinguish between accidental damage, theft, breakdown, road use and liability exposures. Cover can also vary when equipment is hired, transported, stored or operated outside its usual location. Accurate equipment descriptions and use details are essential.
Excavators, loaders and other mobile plant may operate in changing conditions and across multiple sites. Insurance arrangements should reflect the machinery's declared use, location and exposure to damage or theft. Road registration or movement between sites may introduce separate requirements. The policy should be checked for its treatment of operating risks.
Portable equipment can be moved frequently between vehicles, storage facilities and worksites. Theft and accidental damage are common concerns, but policy conditions can depend on where items are kept and how they are secured. An item limit, excess or unattended-vehicle restriction may affect a claim. Equipment records help identify what is intended to be insured.
Hiring machinery can create contractual responsibility for equipment owned by another party. Hire agreements may impose insurance obligations that are not automatically addressed by an existing policy. Cover for hired-in plant and equipment hired to others can differ. The contract and policy should be reviewed together.
Accidental external damage and internal mechanical breakdown are not necessarily covered in the same way. Machinery condition, maintenance, intended use and operator practices can affect insurance terms. Some policies exclude wear, gradual deterioration or specified mechanical failures. Any breakdown extension should be checked carefully.
We consider what the machinery is, how it is used and whether the proposed policy reflects the operational arrangements.
We encourage clients to identify insurance obligations arising from equipment hire and subcontracting arrangements.
Our construction insurance focus helps us discuss equipment risks alongside the broader activities of a building business.
Tell us about the project and Jenny Hoang will come back to you with questions or terms. Prefer to talk? Call 0468 034 450, Monday to Friday, 9:00am to 5:00pm.
Discuss plant and machinery insurance with PCIC Insurance. Call 0468 034 450 or email jenny@pcicinsurance.com.au.
No obligation to proceed. Monday to Friday, 9:00am to 5:00pm.
Identify the machinery, descriptions, relevant values, ownership and the purposes for which each item is used.
Discuss regular worksites, transport, storage, hire arrangements and any unusual operating conditions.
Review available insured events, excesses, item limits, exclusions and conditions based on the insurer's proposed terms.
New purchases, disposals, changes in use and different hire arrangements may require an insurance review.
Many insurers consider eligible mobile construction equipment, including excavators and skid steer loaders. Acceptance and cover depend on the machinery, use, value, location and operating conditions. Some activities or equipment types may require specialist consideration.
Not necessarily. Hired-in equipment often needs to be declared or specifically included under the applicable wording. The hire contract may also require particular insurance terms, so the two documents should be checked together.
Breakdown is not automatically included in every plant policy. Some policies focus on specified accidental damage, while mechanical breakdown may require different cover or remain excluded. Review the exact terms for the equipment concerned.